Note: This article is general information, not insurance advice. Premiums, credits, coverage and eligibility are decided by insurers and depend on many factors. Talk with your licensed insurance agent about your property.
Are Florida commercial property premiums really going down?
In one important part of the market, yes. The Florida Surplus Lines Service Office (FSLSO) reports every month on policies written by surplus lines insurers, which cover many risks that standard carriers do not write. Its September 2026 premium report shows:
- Commercial property premium was down 16% year to date through September, to $4.54 billion.
- Policy count was up 22% over the same period.
- Average cost per policy fell 31%, to $15,628.
- Commercial general liability premium was down 4%, with policy count essentially unchanged from 2025.
More policies for less total premium points to a more competitive market for property coverage. It is an average across many buildings, though, not a promise about any one renewal.
What about liability?
Liability has not followed property down. An Insurance Journal report published Nov. 9, 2026 looked at data from Advocate Technologies covering more than 1,000 Florida multifamily properties (condominiums excluded). The median property premium per door fell from $797 in early 2025 to $479 in April 2026. Over the same stretch, the median liability premium per door rose slightly, from $167 to $169, and a smaller, more recent sample came in higher. The firm's report also cautioned that "property softening is cyclical and can reverse on one bad catastrophe season."
The takeaway for owners: the property side of the bill may have room to move, but the condition of the building, and the hazards on the site, still matter to the people pricing it.
What do underwriters want to know about a building?
Every insurer has its own questions, and your agent is the best guide to them. In our experience, the conversation usually comes back to a few physical items:
- The roof. Age, covering type, visible damage, ponding, flashing and the condition of rooftop equipment.
- Major systems. The age and visible condition of HVAC equipment, electrical distribution and plumbing.
- Water intrusion. Stains, failed sealants, clogged drains and grading that sends water toward the building. Our drainage warning signs guide covers what to look for.
- Site conditions. Trip hazards, damaged walkways and stairs, and lighting in common areas often come up in liability conversations.
- Records. Roof warranties, permits, service records and repair invoices that show the building has been maintained.
How current documentation helps at renewal
When a market softens, owners and agents often shop coverage. Clear, current information about the building makes that easier. It can also show you what to fix before an insurer's own inspection does.
Focused Systems Review (Scope 1)
Our Scope 1 — Focused Systems Review evaluates selected systems you choose ahead of time, such as the roof and visible drainage, HVAC equipment, electrical distribution and plumbing. You receive a written report with photographs, observed concerns and clearly stated access limitations. It is not a full building inspection or a Property Condition Assessment, and it is often the right size for a renewal question.
Drone inspection services
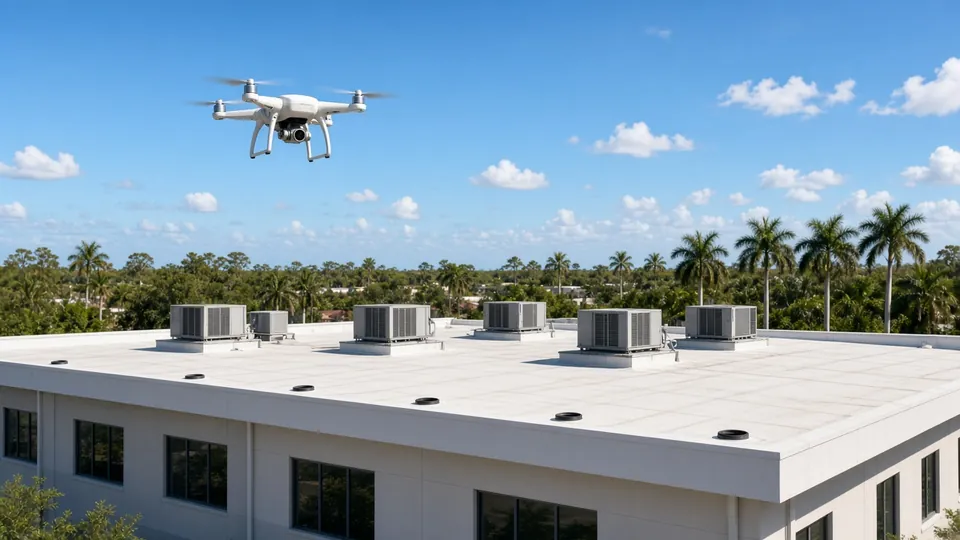
Drone imagery documents large or hard-to-reach roofs, building exteriors and sites. The photographs and video can supplement a systems review or stand on their own as a dated record of roof condition. Aerial images do not by themselves establish structural integrity or equipment performance.
Need the full picture?
A Scope 2 — Standard Commercial Inspection covers the whole building, and Scope 3 — Commercial Inspection + Five-Year Capital Planning adds repair cost opinions and a five-year reserve outlook.
Practical steps before your next renewal
- Ask your agent, well before renewal, what the insurers they work with want to see for your building.
- Gather roof, HVAC and electrical records, warranties and permits.
- Get current photos and findings on the roof and major systems.
- Repair the small items, such as damaged flashing, failed sealants, clogged drains and trip hazards.
- Keep the report and invoices together so your agent can answer questions quickly.
We serve apartment, office, retail, industrial and church properties across Jacksonville, Tallahassee, Gainesville, Ocala, Lake City and throughout Florida, Georgia and Alabama. See what our reports include.
Frequently asked questions
Are commercial property insurance premiums going down in Florida?
In the surplus lines market, yes on average. The Florida Surplus Lines Service Office reported commercial property premium down 16% through September 2026, with policy count up 22% and average cost per policy down 31% to $15,628. Individual renewals vary.
Is commercial liability insurance also getting cheaper?
Not in the same way. FSLSO reported commercial general liability premium down 4% through September 2026. Data cited by Insurance Journal show Florida multifamily liability premiums per door edging up while property premiums fell sharply.
Will an inspection lower my insurance premium?
No inspection can guarantee a premium, credit or coverage decision. Those belong to the insurer. Current, photo-supported findings help you and your agent present the building accurately and fix problems before an insurer's own review.
What is a Focused Systems Review?
It is a targeted inspection of selected building systems, such as the roof, HVAC, electrical and plumbing, with a written report, photographs and stated limitations. It is not a full building inspection or a Property Condition Assessment.
Can a drone inspection document my commercial roof?
Yes. Drone imagery captures roof coverings, drains and rooftop equipment that are hard to see from the ground. It documents visible conditions and does not by itself establish structural integrity or equipment performance.
Renewing or shopping coverage soon? Tell us about the building and which systems your agent is asking about, and we'll recommend the right scope.
Sources
- Florida Surplus Lines Service Office, “September 2026 | FL Premium Report,” Oct. 2, 2026
- FSLSO, “A Monthly Snapshot of the Florida Surplus Lines Market: September 2026” (PDF)
- Insurance Journal, “Southeast States’ Reforms May Have Helped Property Premiums but Data Show Multifamily Liability Rates Up,” Nov. 9, 2026
Images in this article are AI-generated illustrations, not actual High Mark inspections or client properties. This article is general information and does not replace the written scope in your inspection agreement.